What Is Crypto‑Backed Lending?
Crypto‑backed lending is a secured‑loan model where you pledge Bitcoin, Ethereum, or other digital assets as collateral to borrow fiat currency or stablecoins, without a credit check. A smart contract or licensed custodian holds your coins while you repay. Loan‑to‑Value (LTV) ratios typically range from 30 % to 60 %. Example: Stake $10,000 in BTC at 50 % LTV ➜ receive $5,000 in USDC, pay interest monthly, reclaim collateral at repayment.
Related term: peer‑to‑peer lending➜ some platforms match borrowers directly with liquidity providers rather than lending off their own balance sheet.
Key Benefits of Crypto-Backed Lending
| # | Benefit | Why It Matters |
|---|---|---|
| 1 | Access liquidity without selling | Preserve upside potential & defer capital‑gains tax events |
| 2 | Rapid approval (minutes) | Automated smart contracts, 24/7 funding |
| 3 | No credit score needed | Collateral, not creditworthiness, secures the loan |
| 4 | Competitive rates | Secured loans often 5-12% APR, lower than credit-card cash advances |
| 5 | Flexible repayment | Many platforms allow interest-only or early repayment with no penalty |
| 6 | Diversification tool | Unlock cash for expenses or investments without shrinking crypto stack |
Case Study: Sarah’s Home Renovation
Scenario: Sarah holds 2 BTC (≈ $100 k) and needs $30 k for a kitchen remodel.
Loan setup: She pledges 0.8 BTC (≈ $40 k) as collateral. At a 50 % LTV, she borrows $20 k at 8 % APR for 12 months.
Outcome: Sarah keeps ownership of her BTC, avoids $4.5 k in capital‑gains tax, and completes her renovation.
Risk watch: If BTC falls toward the 80 % LTV liquidation threshold (≈ $50 k/BTC), Sarah plans to add USDC collateral or make an early repayment to stay safe.
Subscribe To The NGRAVE Blog
Get the latest insights on crypto, security, blockchain, and more.
By signing up, you agree to receive our marketing offers following our Privacy Policy. You can unsubscribe at any time.
Understanding the Risks and Considerations
- Market Volatility / Liquidation Risk, If collateral value drops below the liquidation threshold, the platform will auto‑sell assets to cover the loan. Keep buffer LTV ≤ 40 % or top‑up collateral fast.
- Interest & Fees, Compare APR, origination, liquidation, and withdrawal fees across platforms.
- Regulatory Uncertainty, Rules differ by country; some regions (EU/UK) restrict retail crypto loans.
- Counterparty Risk, Centralized providers can fail. Use audited, licensed platforms and prefer self‑custody escrow when possible.
- Tax Implications, Interest is usually deductible; liquidations may realize capital gains. Consult a tax professional.
Crypto‑Backed Lending vs. Traditional Lending: A 2025 Snapshot
| Feature | Crypto-Backed Lending | Traditional Lending |
|---|---|---|
| Credit Check | ❌ None | ✅ Required |
| Approval Time | Minutes to hours | Days to weeks |
| Collateral | Bitcoin, ETH, etc. | Property, vehicles, etc. |
| Interest Rates | 5-15% | 3-25% |
| Access Hours | 24/7 | Business hours |
| Liquidation Driver | Market volatility | Payment default |
| Regulation | Emerging (MiCA, US state NMLS) | Established |
*APR varies by platform, LTV, and asset. Always compare offers.
Best Practices for Potential Borrowers
- Research Platforms Thoroughly, Look for SOC‑2 reports, proof‑of‑reserves, and insurance coverage.
- Borrow Conservatively, LTV ≤ 40 % gives about a 40 % price‑drop cushion.
- Enable Alerts, Set SMS/email triggers at 70 % and 80 % LTV.
- Keep Emergency Collateral, Hold liquid stablecoins to top up fast.
- Read the Fine Print, Some platforms allow partial liquidations, others liquidate 100%.
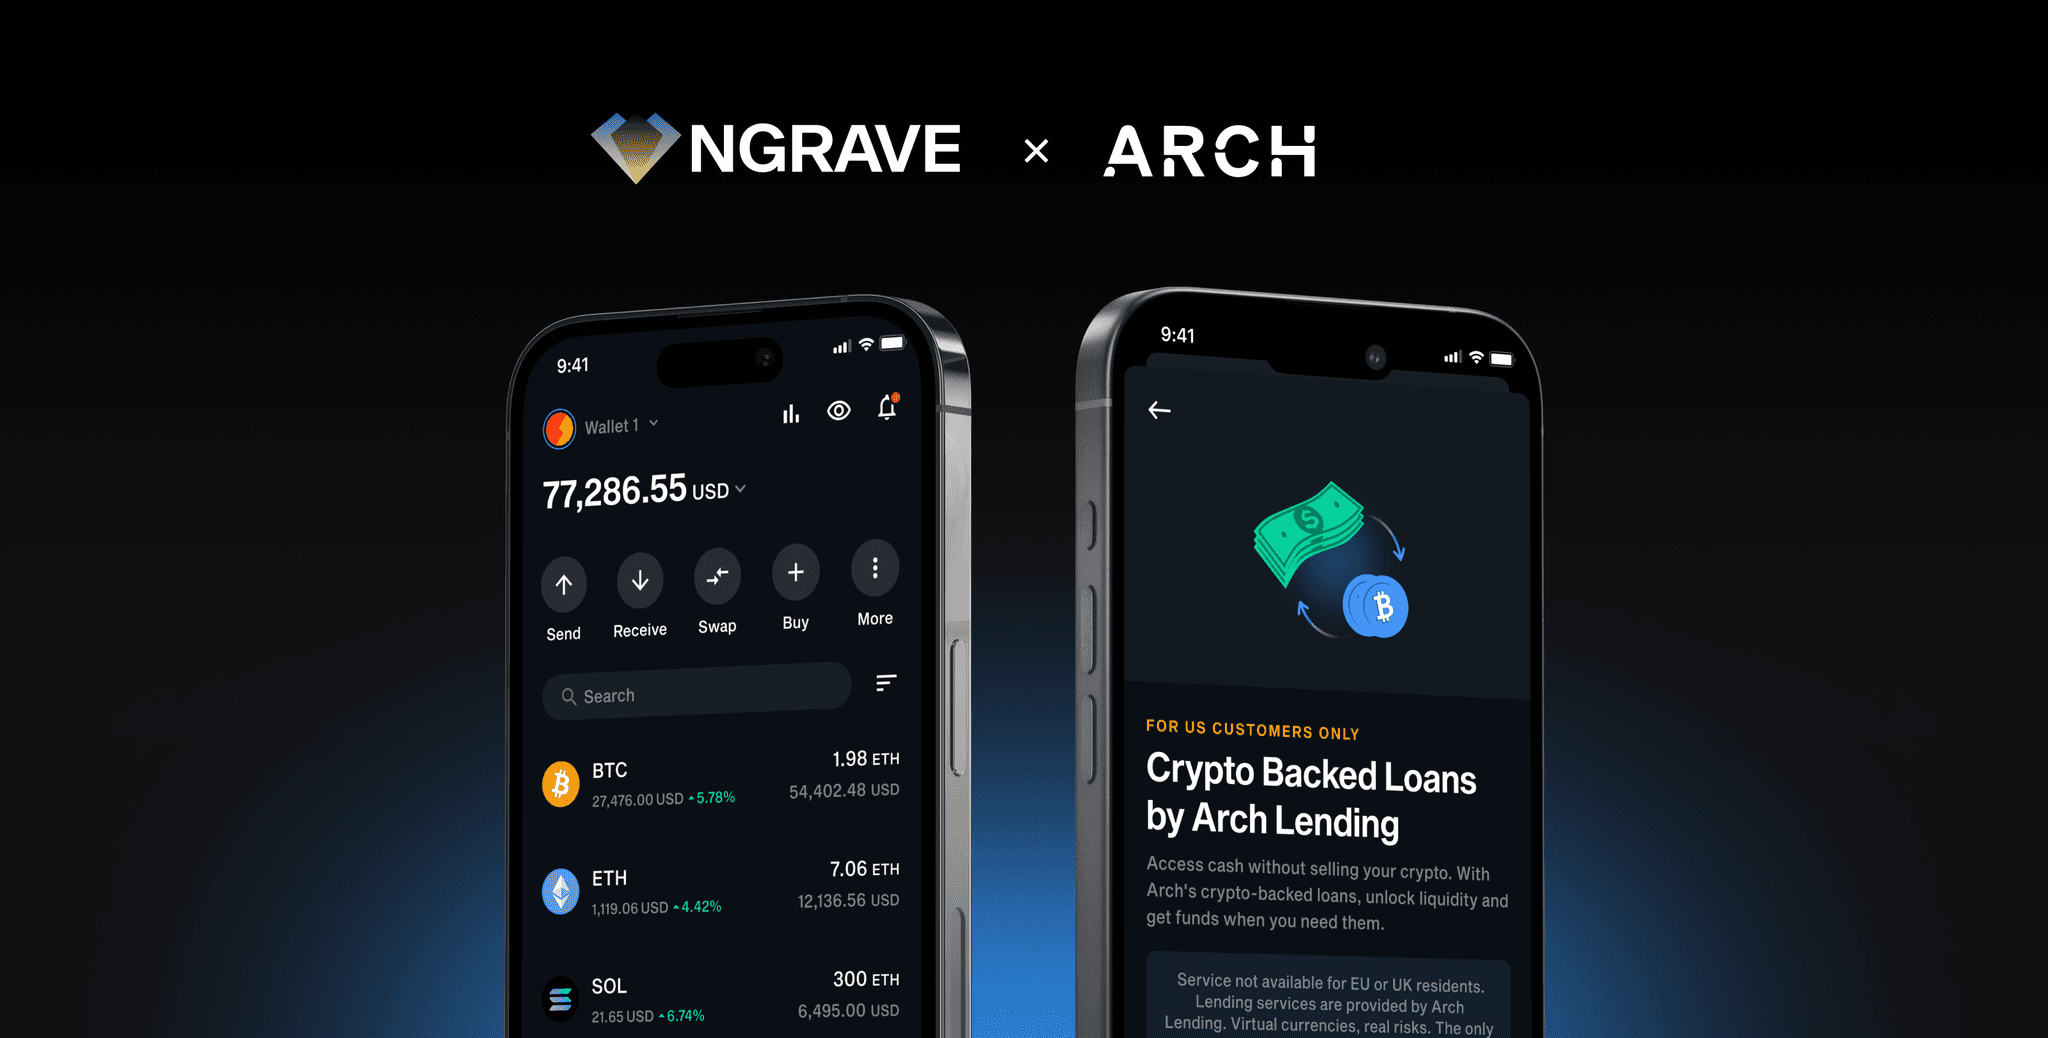
How to Get a Crypto-Backed Loan with a Hardware Wallet NGRAVE ZERO
- Update your LIQUID app.
- Open the app and click on the “Loan” tab.
- Choose loan terms powered by Arch’s automated peer-to-peer lending engine.
- Receive USDC or fiat in your NGRAVE wallet within 5 minutes. Smart-contract escrow ensures that funds remain under user control until repayment.
FAQ
- Who can take out Arch’s crypto-backed loan?
- What collateral is accepted to take out Arch’s crypto-backed loan?
- What is the interest rate of Arch’s crypto-backed loan?
- What is the maximum and minimum term for Arch’s crypto-backed loan?
- Which fees apply to Arch’s crypto-backed loan?
- What are the liquidation and margin call thresholds? Can I top up the collateral?
- Where does Arch store the crypto assets used as collateral for its crypto-backed loans?
Conclusion
Crypto‑backed lending is a powerful tool to unlock cash without abandoning long‑term crypto conviction. By choosing secure platforms, maintaining conservative LTV ratios, and closely monitoring positions, borrowers can mitigate volatility risk and harness liquidity responsibly.
Important Disclaimer
Virtual currencies, real risks. The only guarantee in crypto is risk. Learn more
ChainFi Inc’s (dba Arch) crypto-backed loan services are not available to residents of the EU or UK. Access is also restricted to certain U.S. states. To view the list of eligible states, please visit Arch’s FAQs. Use of this service is subject to the Arch Lending Terms and Conditions.
Please note that NGRAVE is not affiliated with Arch and does not provide, manage, or control any of its services. NGRAVE does not assume any responsibility or liability for the services, content, products, or activities offered by Arch.
Crypto-backed loans involve substantial risks, including but not limited to collateral liquidation due to market volatility, loss of assets, and regulatory uncertainty. In addition, borrowing against crypto comes at a cost, including interest, fees, and potential tax implications. You should evaluate these factors carefully before proceeding. This is not financial advice.